
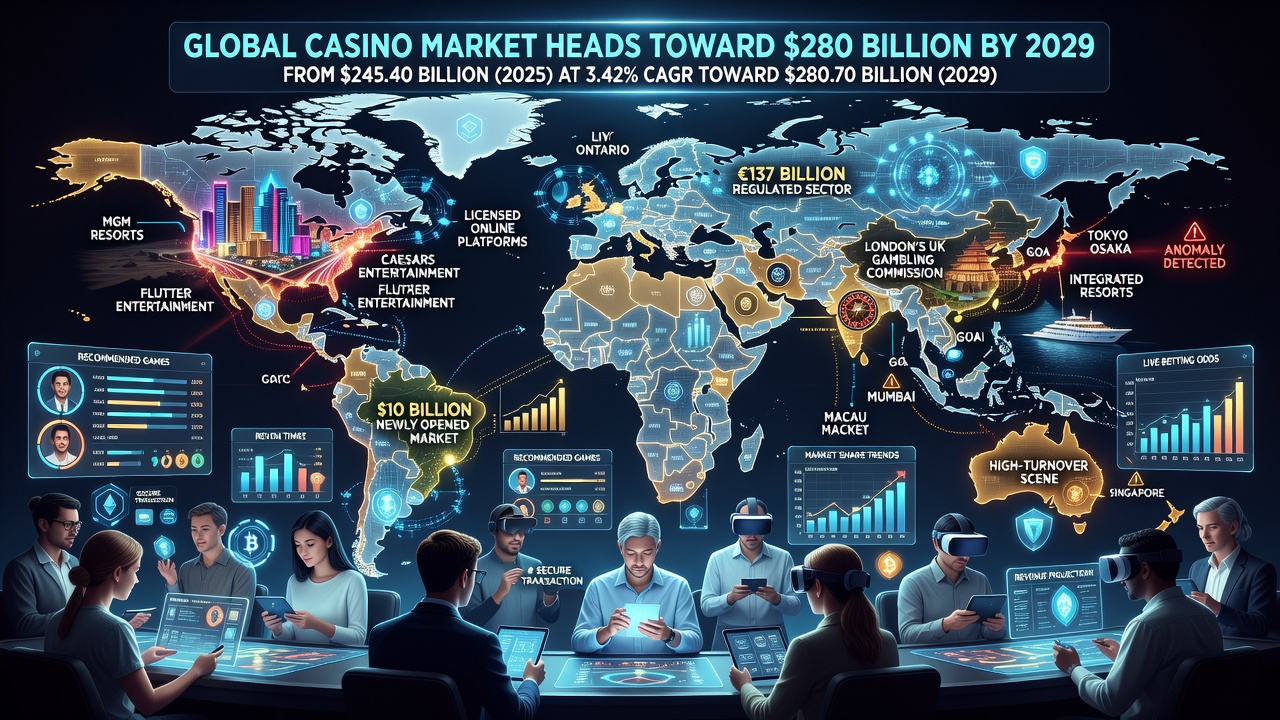
The casino gaming industry is set to expand from a projected $245.40 billion in 2025 to $280.70 billion by 2029, according to Statista figures, implying a compound annual growth rate of 3.42%. That trajectory reflects a decade of structural change: regulated online gambling spreading across new jurisdictions, mobile technology reshaping how people play, and operators using data to hold players' attention longer. The growth is real, but it is uneven, shaped by regulation as much as demand.
Online Gambling Is the Engine, Not the Whole Picture
Online gambling has grown far faster than the wider casino sector. H2 Gambling Capital data shows the online market rising from roughly $37.5 billion in 2015 to more than $81 billion in 2023, a CAGR near 9.6%. That expansion has coincided with the number of casino game users worldwide climbing toward a projected 819 million by 2029. Smartphone penetration and improved connectivity explain much of this, but so does the steady legalisation of online betting and casino products in markets that previously restricted them.
Regional Divergence Defines the Market
Growth is not distributed evenly. The United States remains the largest single market, forecast at $63.17 billion in 2025, propelled by state-by-state regulation and established operators such as MGM Resorts, Flutter Entertainment and Caesars Entertainment. Ontario's open licensing model has driven Canadian growth, with gaming sites reporting $730.7 million in gross revenue in 2024, up 35.2% year-on-year. Brazil's 2023 legislation opened what is estimated to be a $10 billion annual gambling market, though operators face GGR taxation of up to 12% and strict advertising rules. Europe's regulated market reached €137 billion in gross gaming revenue in 2024, with online gambling contributing €55 billion. The UK recorded a £15.1 billion gross gambling yield for 2022-23, even as the Gambling Commission tightens affordability checks and bonus restrictions. Australia, despite high participation rates, saw online gambling turnover climb 165.7% year-on-year within a tightly regulated framework.
Technology Is Reshaping the Product, Not Just the Distribution
Operators are increasingly using data analytics and AI to personalise offers, recommend games, and flag problem patterns in real time. This raises legitimate questions about transparency: personalisation that improves user experience can also intensify engagement in ways regulators are watching closely. Blockchain-based payment verification and fraud detection are being adopted to improve trust, while virtual reality casino formats are moving from novelty toward a more established segment. None of these technologies changes the underlying mathematics of casino games - the house edge remains a fixed structural feature - but they do change how frequently and how intensively people interact with gambling products.
Where the Opportunities and Risks Sit
Markets across Asia-Pacific, Latin America and parts of Africa are opening up as incomes rise and regulatory frameworks mature, while India's growing digital payment infrastructure makes it a market worth watching. Integrated resort projects in Macau, Singapore and Japan show how regulation and investment together can create entirely new destinations for the industry. For operators, the core challenge is not finding growth - it is managing the compliance burden that comes with it: advertising limits, taxation variance, affordability checks, and payment restrictions differ sharply by jurisdiction.
- Regulatory divergence between the US, UK, EU and emerging markets requires distinct compliance strategies for each territory.
- AI-driven personalisation raises both commercial opportunity and responsible-gambling oversight questions.
- Mobile access and improved connectivity remain the single biggest driver of new user growth globally.
The direction of travel is clear enough: more users, more revenue, more regulatory scrutiny. How operators balance commercial growth against consumer protection will likely determine which markets sustain their momentum through 2029 and which face tighter restrictions in response to public and political pressure.